 Google AI
 ChatGPT
 Perplexity
You sold a rental. Now you want an apartment building. The clock is already running. This guide shows you how to fund the deal and keep your tax deferral.
The short answer
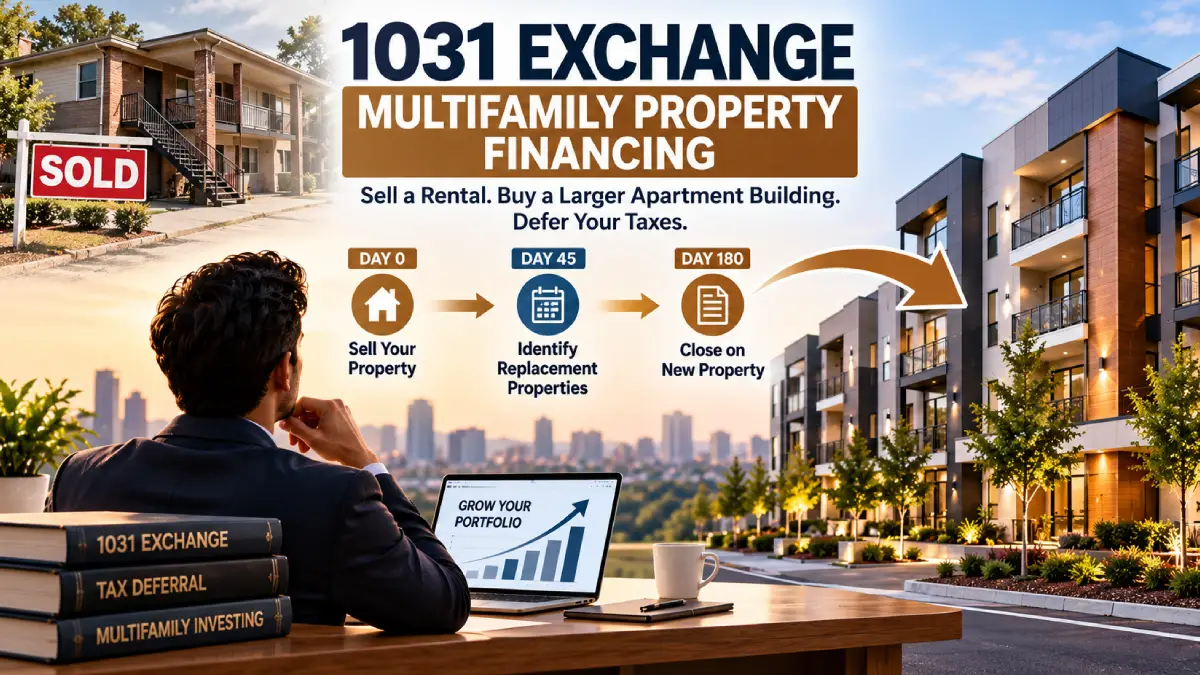
- You have 45 days to name your targets. You have 180 days to close.
- Your new loan must replace your old debt, or you must add cash.
- DSCR loans, agency loans, and bridge loans fit most 1031 deals.
- Line up your lender before you list your old property.
Want a quick read on your deal? Talk to our team or browse our multifamily loan products.
How 1031 Exchange Multifamily Property Financing Works
Section 1031 lets you defer tax when you swap one investment property for another. Since 2018, it covers real property only. You can read the rule in Section 1031 of the tax code.
The flow is simple. You sell your old property. A qualified intermediary (QI) holds the cash. You then buy the new property with that cash plus a new loan.
Here are the steps:
- Hire a QI before you close the sale.
- Close the sale. The QI receives your net proceeds.
- Name your replacement targets in writing within 45 days.
- Get your loan approved and close within 180 days.
- Report the swap on your tax return.
Your lender sits in the middle of steps 3 and 4. A slow loan can sink the whole exchange. That is why smart investors pick a lender first.
Why investors use 1031 exchanges for apartments
A sale can trigger a large tax bill. A swap lets you keep that money working. You can trade a small rental for a bigger building. You can grow rent roll and cash flow faster.
Research backs this up. Professors David Ling and Milena Petrova studied commercial sales for The Real Estate Roundtable. They found that exchange buyers bought replacement property worth about 33% more. That gap was roughly $305,000 to $422,000. Exchange buyers also used less debt than regular buyers.
The same study found a catch. In 88% of cases, the investor later sold the replacement property in a fully taxable sale. So a 1031 defers tax. It does not erase it.
The Rules Your Loan Must Follow
Three rules shape your loan. Break one, and part of your gain becomes taxable. That taxable piece is called boot.
Rule 1: Buy equal or up
The new property must cost at least as much as the net sale price of the old one. A cheaper purchase leaves cash on the table. That cash is boot.
Rule 2: Reinvest all the equity
You must move all net proceeds into the new deal. Any cash you take out is taxed right away.
Rule 3: Replace your debt
The IRS counts a drop in debt as boot. This is called mortgage boot.
Here is a simple example:
- You sell a 10-unit building for $2,000,000.
- You owe $1,000,000 on it.
- Your net equity is about $1,000,000.
To defer all tax, you must buy a property worth at least $2,000,000. You also need a new loan of at least $1,000,000. Or you can add your own cash to cover any gap.
Cash can offset a debt gap. A bigger loan can also offset it. But new debt cannot make up for cash you took out.
Now see how leverage helps. Say you reinvest $1,000,000 of equity and use a 75% loan. You can buy a property near $4,000,000. The loan would be about $3,000,000. That is how a small building becomes a large one.
For details on rules and forms, see the IRS page on like-kind exchanges.
Who Can Buy: The Same Taxpayer Rule
The seller and the buyer must be the same taxpayer. Title must match.
- If you sell as an individual, buy as an individual. Or buy through a single-member LLC that the IRS ignores for tax.
- If a single-member LLC sells, that LLC or its sole owner must buy.
- If a multi-member LLC or partnership sells, the same entity must buy.
Partnerships with partners who want different paths need early planning. Options include a tenant-in-common split or a drop-and-swap. Talk to your tax advisor before you list. Tell your lender about your entity too. Many lenders need extra time to review vesting.
The Clock: 45 Days and 180 Days
Both clocks start the day your old property closes. They run at the same time. There are no free extensions.
| Phase | Day | What must happen |
| Sale closes | Day 0 | The QI receives your net proceeds |
| Identification | Day 45 | You send your written list to the QI by midnight |
| Closing | Day 180 | You take title to the new property |
The three ways to name properties
- Three-property rule: Name up to three. Value does not matter.
- 200% rule: Name any number. Their total value must stay under 200% of what you sold.
- 95% rule: Name any number of any value. But you must buy at least 95% of the total.
Most investors use the three-property rule. It is simple. It also gives you backups.
Get a lender before day 45
Do not name a property you cannot finance. If the loan fails on day 50, you cannot add a new target. The exchange may fail with it.
So ask your lender three questions before you name anything:
- Will you lend on this property type and unit count?
- How many days do you need from signed contract to closing?
- What do you need from me, and how fast?
The tax return trap
This is the mistake that surprises people. Your 180 days end on the earlier of two dates. One is day 180. The other is your tax return due date, with extensions. The rule sits in Treasury Regulation 1.1031(k)-1.
Say you close a sale in November. Day 180 falls in May. But your April return due date comes first. Without an extension, your window shrinks.
The fix is easy. File an extension. Individuals use Form 4868. Partnerships and corporations use Form 7004. Then close the purchase. File your return after that.
| Example date | What happens |
| November 15 | Old property closes. Day 0 starts |
| December 30 | Day 45. Your list is due |
| April 15 | Return due. File an extension if you have not closed |
| May 14 | Day 180. Your purchase must close |
Loan Options for Your Replacement Property
No single loan wins every time. Your choice depends on speed, price, property type, and your plan for the building.
| Loan type | Typical speed | What the lender checks | Best for |
| DSCR loan | About 3 to 4 weeks | Rent and property cash flow | Small and mid-size buildings |
| Fannie Mae or Freddie Mac | Often 45 to 90 days | Net operating income | Stable buildings with 5+ units |
| Bridge loan | As fast as 1 to 2 weeks | Property value and your exit plan | Tight deadlines and value-add deals |
| FHA/HUD | Several months | Property quality and cash flow | Long timelines, large deals |
| Bank loan | Often 45 to 90 days | Your income and tax returns | Investors with local bank ties |
Speeds change by lender, market, and file quality. Treat these as ranges, not promises.
DSCR loans
A DSCR loan looks at the property, not your tax returns. That makes it a fast and popular choice for 1031 buyers. Read more in our guide to DSCR loans for multifamily.
The formula is simple:
DSCR = Net Operating Income ÷ Annual Debt Service
Say a building earns $150,000 in rent. Expenses are $40,000. Net operating income is $110,000. Your yearly loan payment is $105,000. Your DSCR is 1.05. That is thin. Many lenders want 1.20 to 1.25 or more.
Now say rent is $180,000. Net operating income is $140,000. The same payment gives a DSCR of 1.33. That can unlock better pricing.
Note that lenders differ. Some add taxes and insurance to the payment side. Ask how your lender counts them.
Learn more about investor loan requirements before you apply.
For background on the ratio, see Investopedia on debt service coverage.
Fannie Mae and Freddie Mac loans
Agency loans suit stable buildings with five or more units. They often offer low fixed rates. They are usually non-recourse. That means the lender looks to the property, not your personal assets, if the loan fails.
Non-recourse has limits. Lenders add “bad boy” carve-outs. Fraud, bankruptcy, and unapproved debt can make you personally liable.
Small deals have good options now:
- Fannie Mae Small Loans go up to about $9 million.
- Freddie Mac Conventional Small now covers loans from $2 million to $10 million. Freddie announced this change in April 2026 and retired its old Small Balance Loan program.
Many older guides still list the old Freddie range. Check current terms before you plan your deal.
Agency loans take longer than DSCR or bridge loans. So start early. See our overview of Fannie Mae and Freddie Mac multifamily loans.
Bridge loans
A bridge loan is short-term money. It helps when the building needs work or has low occupancy. It also helps when time is short. Terms often run 6 to 36 months. Many are interest-only.
The plan has three phases:
- Buy: Close fast with bridge funds.
- Improve: Renovate, lease up, and raise income.
- Refinance: Move into a long-term agency or bank loan.
Bridge debt costs more than long-term debt. Still, it can save a deal. Learn how it works in our guide to multifamily bridge loans.
Bank loans
Local banks can offer fair rates and flexible terms. But they often want full tax returns and personal guarantees. They may also want deposits. Banks can be slow. Ask for a written timeline.
FHA and HUD loans
HUD-backed loans can offer long terms and high leverage. But they take a long time. They fit best when you have a long runway. They may suit a reverse exchange, where you buy first and sell later.
Seller financing
Sometimes the seller of your new property carries part of the price. That can work. But a note on your old property needs care. A seller note you receive is not cash. The IRS may treat it as boot unless you structure it well.
Common fixes include selling the note for cash before closing. You can also have the new seller accept the note as part of payment. Always get tax advice first.
Match the Loan to the Building Size
| Units | Common loan paths |
| 1 to 4 | DSCR loan, bank loan, or conventional loan |
| 5 to 20 | Agency small loan, commercial DSCR loan, bridge loan |
| 21 to 40+ | Fannie Mae, Freddie Mac, or HUD. Bridge for value-add |
Not sure where you fit? See our loan products or contact a loan advisor.
The Hidden Boot Trap: Loan Fees
Most guides skip this point. It costs investors real money.
Some closing costs can come from exchange funds. These are usual costs of the deal. Examples are QI fees, escrow fees, recording fees, and title costs.
Loan costs are different. Points, lender appraisals, and lender title policies are loan costs. Most tax advisors say paying them from exchange funds creates boot. Some advisors take a softer view when financing is a condition of the contract. The safe move is to pay loan fees with your own cash.
So plan for it. Keep extra cash outside the exchange. Ask your QI and tax advisor to review the closing statement. Do this before closing day.
Costs of Selling Without a Swap
Why go through all this? Because a taxable sale can be harsh. Gains can face several layers of tax:
- Federal long-term capital gains tax of 0%, 15%, or 20%
- A 3.8% Net Investment Income Tax for higher earners, under Section 1411
- Up to 25% on depreciation you claimed, under Section 1250
- State income tax, which can reach 13.3% in California
In a high-tax state, these layers can take roughly 37% to 42% of a large gain. A swap defers that bill. It leaves more money to buy the next building.
For a plain-English primer, see Investopedia on 1031 exchanges.
What Lenders Ask For
Gather your file early. Lenders move faster with a clean package.
- Current rent roll and signed leases
- Trailing 12-month income and expense report
- Purchase contract with your 1031 assignment language
- QI agreement and escrow details
- LLC documents, operating agreement, and EIN letter
- Repair history and any capital plan
- Your bank statements for liquidity
- A list of other properties you own
Lenders also check three numbers:
- DSCR: Often 1.20 to 1.25 or higher
- LTV: Often up to 75% to 80% on stable deals
- Reserves: Often several months of payments in cash
Terms vary. Ask for a pre-approval before you list your old property. A pre-approval tells you how much you can borrow. It also helps you set a target price.
Your Step-by-Step Plan
- Before you list: Get pre-approved. Pick a QI. Talk to your tax advisor.
- Before closing the sale: Add 1031 language to the contract. Set up the QI account.
- Day 0 to 45: Shop for targets. Confirm financing on each one. Send your written list.
- Day 46 to 180: Order the appraisal and reports. Close the loan. Close the purchase.
- Tax time: File Form 8824 with your return.
If you need to buy first, ask about a reverse exchange. It adds cost and legal steps. Lenders may also hesitate to lend to the holding entity. Plan well ahead.
When You Need to Buy First: Reverse and Improvement Exchanges
Sometimes the right building shows up before you sell. A reverse exchange lets you buy first. A third party holds title to one of the properties for a time. The same 45 and 180 day clocks apply.
Reverse deals add cost and legal steps. Some lenders will not lend to the holding entity. Others need more time. Ask your lender about this on day one. Do not wait until you find the building.
An improvement exchange helps with fixer-uppers. It lets exchange funds pay for work on the new property. The work must be done, and the property must be in your hands, within the 180 days. Without this tool, repair money spent after closing may not count toward your price.
Both paths need a QI who has done them before. Ask how many they have closed.
What to Do If Your Loan Runs Late
Delays happen. An appraisal comes back low. A lender asks for one more file. Here is how to stay calm.
- Name backups. The three-property rule lets you list three targets. Use all three.
- Ask about a bridge loan. A bridge can close fast and give you time to refinance. See our guide to bridge loans for multifamily.
- Add cash. If the loan comes in smaller, extra cash can cover the gap and protect your deferral.
- Check a Delaware statutory trust. Some investors name a trust interest as a backup. It is a passive option. Talk to your advisor about the trade-offs.
A good lender will tell you early if a deal looks risky. That warning is worth more than a low rate.
Can You Refinance After the Exchange?
Many investors ask this. The answer needs care. A cash-out refinance soon after you close can look like you took cash out of the swap. Some advisors suggest a long gap. Others suggest taking the loan before you sell the old property instead. The IRS has no bright line here. Ask your tax advisor before you act.
Reporting Your Exchange
You report the swap on IRS Form 8824. It has three parts:
- Part I: Describes the properties and dates
- Part II: Covers swaps with related parties
- Part III: Shows gain, boot, deferred gain, and basis
The related-party rule has a two-year hold. If you sell early, the deferral can end.
Your new basis equals the purchase price minus the deferred gain. The old basis carries over and keeps its depreciation schedule. Any new money you add starts a fresh schedule. Residential rental buildings use 27.5 years.
State rules
Most states follow the federal rule. Some add steps:
- California requires annual filings on out-of-state swaps and taxes the deferred gain later.
- Oregon, Montana, and Massachusetts have similar tracking rules.
- Some states require withholding at sale unless you file an exemption through your QI.
Audit window
The usual audit window is three years. It grows to six years when you omit more than 25% of your gross income. Keep your QI agreement, closing statements, ID letter, and lender file.
Common Mistakes to Avoid
- Naming a property before you confirm financing
- Missing the tax return date after a late-year sale
- Paying loan fees from exchange funds
- Taking title in the wrong entity
- Taking less debt than you paid off, with no cash to cover the gap
- Waiting to meet your lender until after you sell
Ready to Finance Your Replacement Property?
The best time to find a lender is before you list your old property. The second best time is today. Tell us about your deal. We will help you size the loan, check your timeline, and pick a path that fits.
Start with our contact page, see the full loan product lineup, or head back to the Multifamily Lender home page.
FAQs
Can I use a DSCR loan for a 1031 exchange?
Yes. A DSCR loan can fund the replacement property. The lender checks the building’s cash flow. That helps you move fast. Make sure the vesting matches your 1031 rules.
How fast can I close a 1031 multifamily loan?
It depends on the loan. Bridge loans can close in one to two weeks. DSCR loans often take three to four weeks. Agency loans often take 45 to 90 days.
What if my loan falls through after day 45?
You cannot add new properties after day 45. You must close on one you named. That is why you should confirm financing first. Name backups too.
Can I use a 1031 exchange to buy a fixer-upper?
Yes. A bridge loan can help. Keep in mind that work done after closing may not count toward the price unless you use an improvement exchange. Ask your QI about it.
This guide is general information. It is not tax or legal advice. Talk to a tax advisor and a qualified intermediary about your own facts.