 Google AI
 ChatGPT
 Perplexity
When it comes to investment property loans, lenders typically look at certain factors. There are investment property loan requirements that lenders look at.
The fundamentals of every investment property loan ultimately are the same few underwriting questions to be addressed, credit, down payment, debt ratios, and reserves. Learning them beforehand can make for a seamless closing, or it can be a deal that’s stalled before it closes.
Credit Score
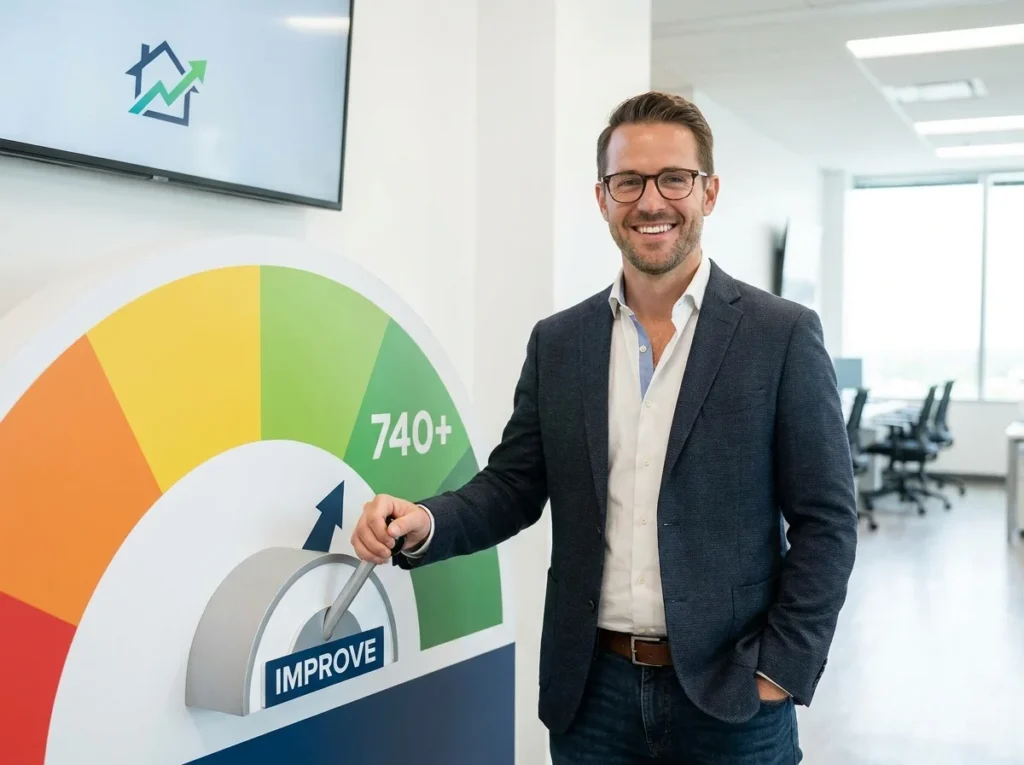
The average credit score a conventional investment property loan will require is between 680 and 720, with 740+ considered the best credit score for a conventional investment property loan. Private and hard money lenders don’t look at this as much, however, and will instead focus on the equity and income potential in the property, making it possible to obtain financing with a score below 600 when the deal itself is a strong one.
Down Payment by Property Size
The down payment depends on the size of the property:
- 1-4 units: 20-25% minimum
- 5+ units: 25-35% (Freddie Mac, Fannie Mae, or portfolio financing)
The larger the down payment, the better the rate.
Get the full guide about Investment Property Loan Rates for Multifamily: A 2026 Market Outlook
Debt-to-Income Ratio
Lenders are looking for a DTI ratio of 43% or less. With rental properties, the lender assumes that they are able to collect 75% of the gross projected rent, which is the payment amount, and the other 25% is the vacancy and maintenance risk.
Cash Reserves
Have at least 6 to 12 months of PITI (principal, interest, taxes, insurance) in liquid reserves per financed property. The lender’s assurance that an unexpected repair or vacancy will not jeopardize the loan.
Choosing the Right Loan Type for Your Deal
After the financial issues are settled, the type of loan to use will rely on the type of property and the strategy used.
DSCR Loans for Cash-Flowing Properties
DSCR loans are almost all income based on the property and not the investor’s personal tax returns, making them great for investors with a lot of properties or complicated tax returns. The typical lender will expect a 1.25x or higher DSCR. To see how this ratio is calculated and how it fits into your strategy, read our full DSCR loan guide or explore our DSCR loan program directly.
Self-Employed and No-Doc Options
Lite-doc programs enable you to qualify with 12 to 24 months of bank statements if your qualifying income is lowered due to tax write-offs. There are also private capital choices for investors with high net-worths that don’t require any income verification. See our guide to no-doc multifamily loans for an answer to precisely who qualifies, or check out our no-doc and lite loan programs here.
Construction and Renovation Loans
Significant renovation and “ground-up” projects involve a pro forma, a line item budget, and a licensed contractor, where draws are made once tasks are finished. Check out our step-by-step guide to ground-up construction financing or our construction loan program.
Private and Bridge Financing When You Don’t Fit the Box
What is the solution when you don’t fit the box? Private lenders and bridge financing lenders rely on the asset’s value and exit strategy when the traditional credit and DTI criteria aren’t applicable. For a comparison of private vs. bank commercial loans, read our article, or for some of the best options, check out our bridge loan lender roundup, or explore our own bridge loan program directly.
Documents You’ll Need to Apply
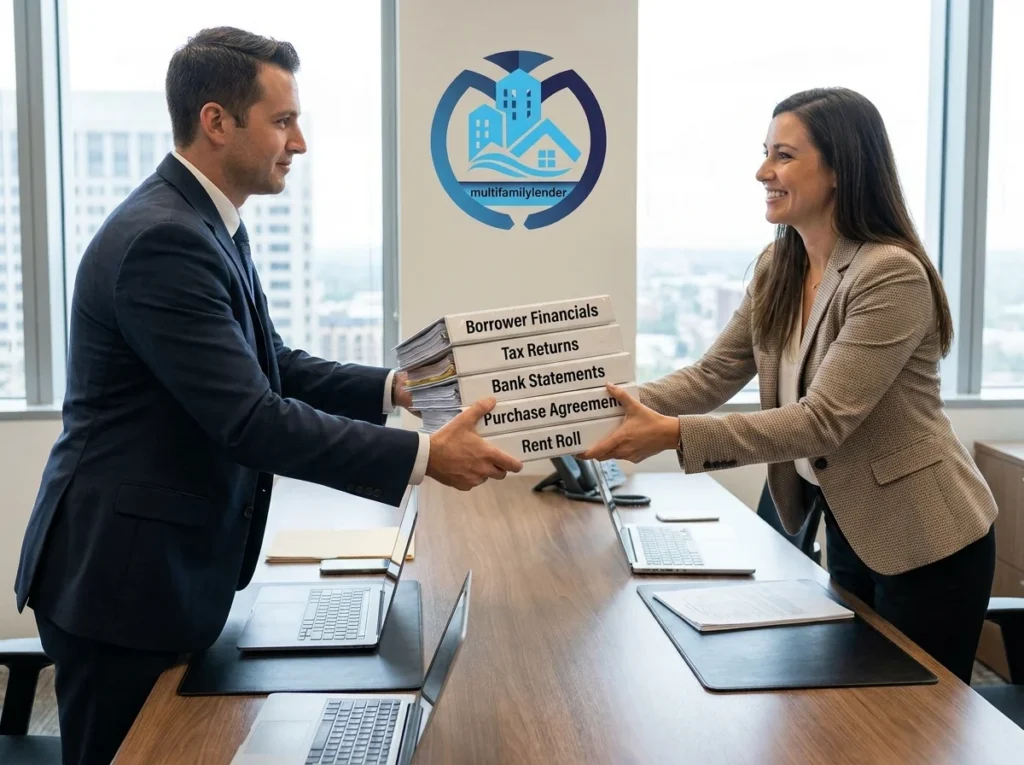
When applying, you’ll need to submit the following documents:
Borrower financials: Two years of tax returns, two to three months of bank/asset statements, personal financial statement, operating statements for any existing rental properties.
Property documentation: Purchase agreement, fully executed, appraisal report, rent roll (if occupied), insurance declaration page, construction budget or pro forma (if applicable).
FAQs
How much is the seasoning requirement for down payment funds?
Answer: Most lenders will ask for 60 days or more of seasoned funds, which is backed up by the last two months of bank statements.
Can I use rental income from a unit I haven’t moved into yet?
Answer: Yes, lenders almost always allow 75% of the gross rents (as outlined on the appraiser’s rent schedule or confirmed on a signed lease).
How many properties can I finance conventionally?
Answer: Fannie and Freddie set the limit for conventional financing at 10 homes per borrower. Other than that, portfolios, private funds, or DSCR loans are unlimited.
Are you set to take the next step? We are able to match you with the ideal loan for your investment, whether you are looking for a conventional or DSCR loan, construction, or private capital, because we have 1,000+ lenders and investors on our team, and have been in business for 30 years. Call us today for a custom consultation.
Are interest payments on an investment property loan tax-deductible?
Answer: Yes, the interest paid on a mortgage secured by an investment property is generally 100% tax-deductible against the income generated by the property. This is a significant tax benefit for investors. However, it’s critical to keep your loans separate; if you refinance the investment property and use part of the cash-out for personal expenses, the interest on that personal portion is no longer deductible (“loan tainting”). Always consult a tax advisor or CPA.
What is the difference between an interest-only payment and a fully amortizing payment on an investment loan?
Answer: An interest-only (IO) payment requires you to pay only the monthly interest accrued on the principal balance; the principal balance itself remains unchanged. A fully amortizing payment includes both a portion of the interest and a portion of the principal, ensuring the loan is fully paid off by the end of the term. IO loans offer lower initial cash flow but do not build equity through repayment, making them popular for short-term strategies such as fix-and-flip or maximizing early-stage cash flow.